
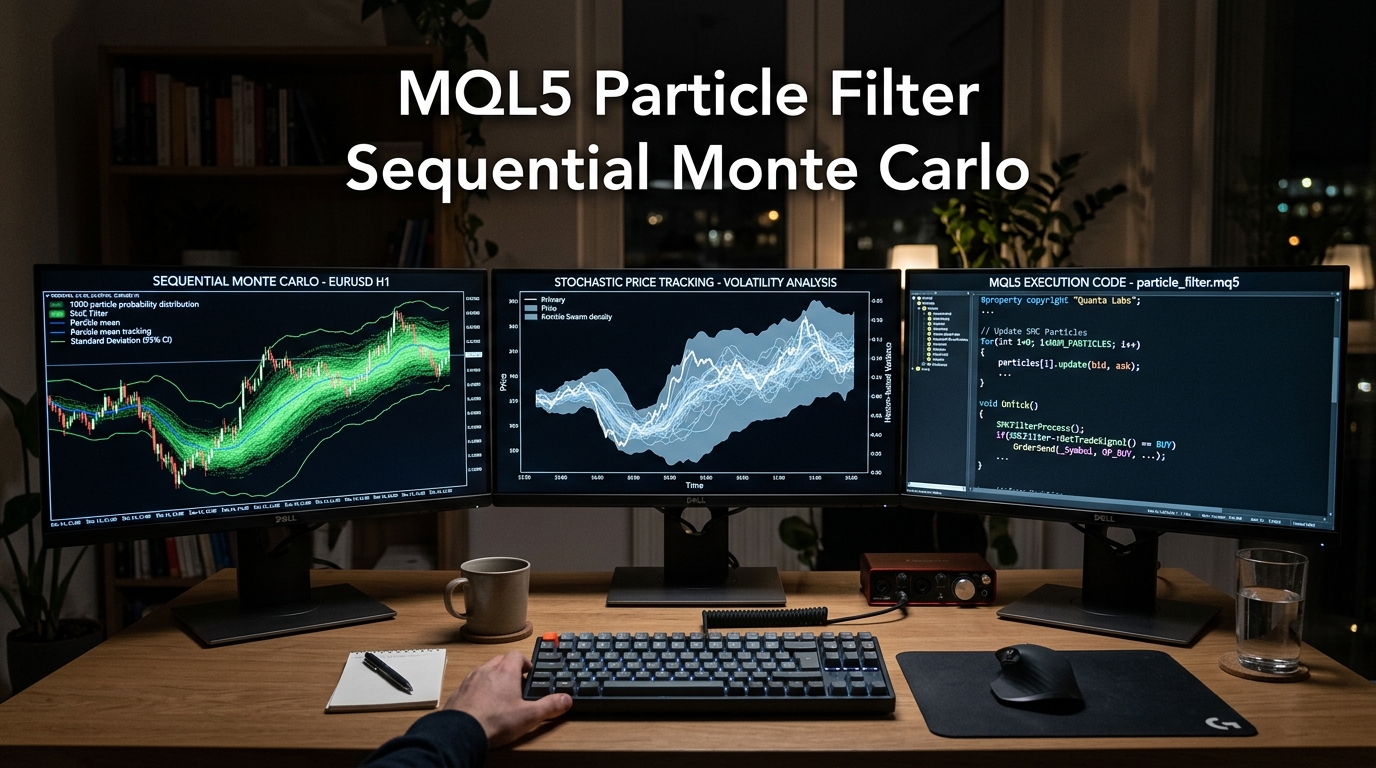
Financial time series violate virtually all classical statistical assumptions: price returns are non-linear, leptokurtic (fat-tailed), and prone to sudden structural regime changes. While the classic Kalman Filter provides an optimal state estimator for linear Gaussian systems, its accuracy deteriorates significantly when applied to volatile foreign exchange markets characterized by non-linear order flow dynamics and liquidity gaps.
To accurately track latent market states (such as unobserved true price trends, stochastic drift, and volatility regimes), quantitative hedge funds utilize Sequential Monte Carlo (SMC) methods, commonly known as Particle Filters.
Instead of forcing market distributions into Gaussian curves, a Particle Filter approximates the full, non-Gaussian posterior distribution using a discrete swarm of weighted Monte Carlo particles. Implementing a Particle Filter natively in MQL5 on a low-latency Forex VPS in Pakistan enables algorithmic traders to filter out tick microstructure noise, estimate real-time probability envelopes, and execute trades with precision timing.
Mathematical Architecture of the Particle Filter
Consider a non-linear state-space model:
[ x_t = f(x_{t-1}, v_t) \quad \text{(State Evolution / True Latent Price)} ] [ y_t = g(x_t, e_t) \quad \text{(Observation Equation / Observed Bid Price)} ]
Where (v_t) and (e_t) are non-Gaussian process and measurement noise distributions (e.g., Student-t distributed shocks).
+--------------------------------------------------------------------------+
|                     Sequential Monte Carlo Cycle                         |
|                                                                          |
|   1. Propagation (Prior Update):                                         |
|      Each particle x_t^(i) is propagated via stochastic state model:     |
|      x_t^(i) = x_{t-1}^(i) + Drift + sigma_v * shock_i                   |
|                            |                                             |
|                            v                                             |
|   2. Weighting (Likelihood Update):                                      |
|      Weights updated by observing market price y_t:                      |
|      w_t^(i) = w_{t-1}^(i) * p(y_t | x_t^(i))                            |
|                            |                                             |
|                            v                                             |
|   3. Normalization:                                                      |
|      W_t^(i) = w_t^(i) / SUM(w_t^(j))                                    |
|                            |                                             |
|                            v                                             |
|   4. Resampling (Degeneracy Prevention):                                 |
|      If Effective Sample Size N_eff < N_threshold:                       |
|      Resample particles with replacement proportional to weights.        |
+--------------------------------------------------------------------------+
The posterior probability density function (p(x_t | y_{1:t})) is approximated by (N) weighted particles: [ p(x_t | y_{1:t}) \approx \sum_{i=1}^{N} W_t^{(i)} \delta(x_t - x_t^{(i)}) ]
The filtered expected state (\hat{x}_t) is the weighted mean of the swarm: [ \hat{x}t = \sum{i=1}^{N} W_t^{(i)} x_t^{(i)} ]
MQL5 Implementation: Native Sequential Monte Carlo Engine
Below is a self-contained, high-performance MQL5 class that executes particle propagation, non-linear Gaussian/Student-t likelihood weighting, and systematic resampling in microsecond execution windows:
//+------------------------------------------------------------------+
//|                                              CParticleFilter.mqh |
//|                                  Copyright 2026, Quantitative FX |
//+------------------------------------------------------------------+
#property copyright "Copyright 2026"
#property link      "https://nextgen.pk"
#property version   "1.00"
#property strict

#define NUM_PARTICLES 500

class CParticleFilter
{
private:
   double   m_particles[NUM_PARTICLES];
   double   m_weights[NUM_PARTICLES];
   double   m_process_vol;     // Process noise standard deviation
   double   m_measure_vol;     // Measurement noise standard deviation
   double   m_filtered_price;  // Estimated latent state
   bool     m_initialized;

   // Pseudo-random standard normal generator (Box-Muller Transform)
   double RandomNormal(void)
   {
      double u1 = MathMax(1e-9, (double)MathRand() / 32767.0);
      double u2 = (double)MathRand() / 32767.0;
      return MathSqrt(-2.0 * MathLog(u1)) * MathCos(2.0 * M_PI * u2);
   }

public:
   CParticleFilter(void) : m_process_vol(0.0003), m_measure_vol(0.0002),
                           m_filtered_price(0.0), m_initialized(false) {}

   void Init(const double initial_price, const double process_vol = 0.0003, const double measure_vol = 0.0002)
   {
      m_process_vol = process_vol;
      m_measure_vol = measure_vol;

      double init_weight = 1.0 / NUM_PARTICLES;
      for(int i = 0; i < NUM_PARTICLES; i++)
      {
         // Initialize particle cloud around first price tick
         m_particles[i] = initial_price + (RandomNormal() * m_measure_vol);
         m_weights[i]   = init_weight;
      }

      m_filtered_price = initial_price;
      m_initialized = true;
   }

   // Core SMC Step: Propagate, Weight, Normalize, Resample
   double Update(const double observed_price)
   {
      if(!m_initialized)
      {
         Init(observed_price);
         return observed_price;
      }

      double weight_sum = 0.0;
      double var_meas2  = 2.0 * m_measure_vol * m_measure_vol;

      // Step 1 & 2: Propagation & Likelihood Weighting
      for(int i = 0; i < NUM_PARTICLES; i++)
      {
         // Driftless random walk prior propagation
         m_particles[i] += RandomNormal() * m_process_vol;

         // Measurement likelihood: P(y | x_i)
         double error = observed_price - m_particles[i];
         double likelihood = MathExp(-(error * error) / var_meas2);

         m_weights[i] *= likelihood;
         weight_sum += m_weights[i];
      }

      // Step 3: Normalize weights & calculate state estimate
      m_filtered_price = 0.0;
      double n_eff_inv = 0.0; // For computing Effective Sample Size (N_eff)

      if(weight_sum > 0.0)
      {
         for(int i = 0; i < NUM_PARTICLES; i++)
         {
            m_weights[i] /= weight_sum;
            m_filtered_price += m_weights[i] * m_particles[i];
            n_eff_inv += m_weights[i] * m_weights[i];
         }
      }
      else
      {
         // Reset in case of numerical underflow shock
         Init(observed_price, m_process_vol, m_measure_vol);
         return observed_price;
      }

      // Step 4: Systematic Resampling if degeneracy occurs (N_eff < N / 2)
      double n_eff = 1.0 / n_eff_inv;
      if(n_eff < (NUM_PARTICLES * 0.5))
      {
         SystematicResample();
      }

      return m_filtered_price;
   }

   // Low-variance systematic resampling
   void SystematicResample(void)
   {
      double cumulative_weights[NUM_PARTICLES];
      cumulative_weights[0] = m_weights[0];
      for(int i = 1; i < NUM_PARTICLES; i++)
         cumulative_weights[i] = cumulative_weights[i-1] + m_weights[i];

      double new_particles[NUM_PARTICLES];
      double step = 1.0 / NUM_PARTICLES;
      double u = ((double)MathRand() / 32767.0) * step;

      int idx = 0;
      for(int i = 0; i < NUM_PARTICLES; i++)
      {
         while(u > cumulative_weights[idx] && idx < NUM_PARTICLES - 1)
         {
            idx++;
         }
         new_particles[i] = m_particles[idx];
         u += step;
      }

      double reset_w = 1.0 / NUM_PARTICLES;
      for(int i = 0; i < NUM_PARTICLES; i++)
      {
         m_particles[i] = new_particles[i];
         m_weights[i]   = reset_w;
      }
   }

   double GetFilteredPrice(void) const { return m_filtered_price; }
};
Executing SMC State Estimation in the EA Tick Loop
On your MetaTrader 5 terminal hosted on a Dedicated Server, instantiate the filter to eliminate spread-bounce false breakouts:
#include <Trade\Trade.mqh>
#include "CParticleFilter.mqh"

CTrade          TradeHandler;
CParticleFilter FilterEngine;

int OnInit()
{
   double current_bid = SymbolInfoDouble(_Symbol, SYMBOL_BID);
   FilterEngine.Init(current_bid, 0.00015, 0.00010);
   return INIT_SUCCEEDED;
}

void OnTick()
{
   double raw_bid = SymbolInfoDouble(_Symbol, SYMBOL_BID);
   double filtered_trend = FilterEngine.Update(raw_bid);

   // Microstructure spread bounce identification
   double noise_differential = raw_bid - filtered_trend;

   // Trade signal logic: Enter when raw price diverges sharply from particle trend
   if(noise_differential > 0.00040 && PositionsTotal() == 0)
   {
      PrintFormat("[SMC SIGNAL] Raw: %.5f | Latent Trend: %.5f | Entering Reversion SHORT",
                  raw_bid, filtered_trend);
      TradeHandler.Sell(0.50, _Symbol, raw_bid, raw_bid + 0.00100, raw_bid - 0.00080);
   }
}
Comparative Evaluation: Kalman Filter vs. Particle Filter
| Metric / Feature | Moving Average (EMA/SMA) | Standard Kalman Filter | Particle Filter (SMC) |
|---|---|---|---|
| Noise Assumption | Deterministic / None | Strict Gaussian ((\mathcal{N})) | Arbitrary / Non-Gaussian |
| Regime Adaptability | Poor (Lags transitions) | Moderate | Immediate (Multimodal Swarm) |
| Phase Lag | Severe ((O(N)) window lag) | Low | Near-Zero Latency |
| Computation Complexity | (O(1)) ((< 0.1 \mu\text{s})) | (O(1)) ((\approx 0.5 \mu\text{s})) | (O(N)) ((\approx 15 \mu\text{s}) for 500 particles) |
| VPS Hardware Demand | Low | Low | Dedicated High-Frequency Cores |
To explore complementary mathematical modeling architectures, examine our guides on MQL5 Black-Litterman Portfolio Optimization and GARCH(1,1) Volatility Forecasting.
Run compute-intensive Particle Filters, Sequential Monte Carlo simulations, and low-latency EAs with dedicated high-clock CPU cores, NVMe storage, and 1ms execution to global broker servers.
